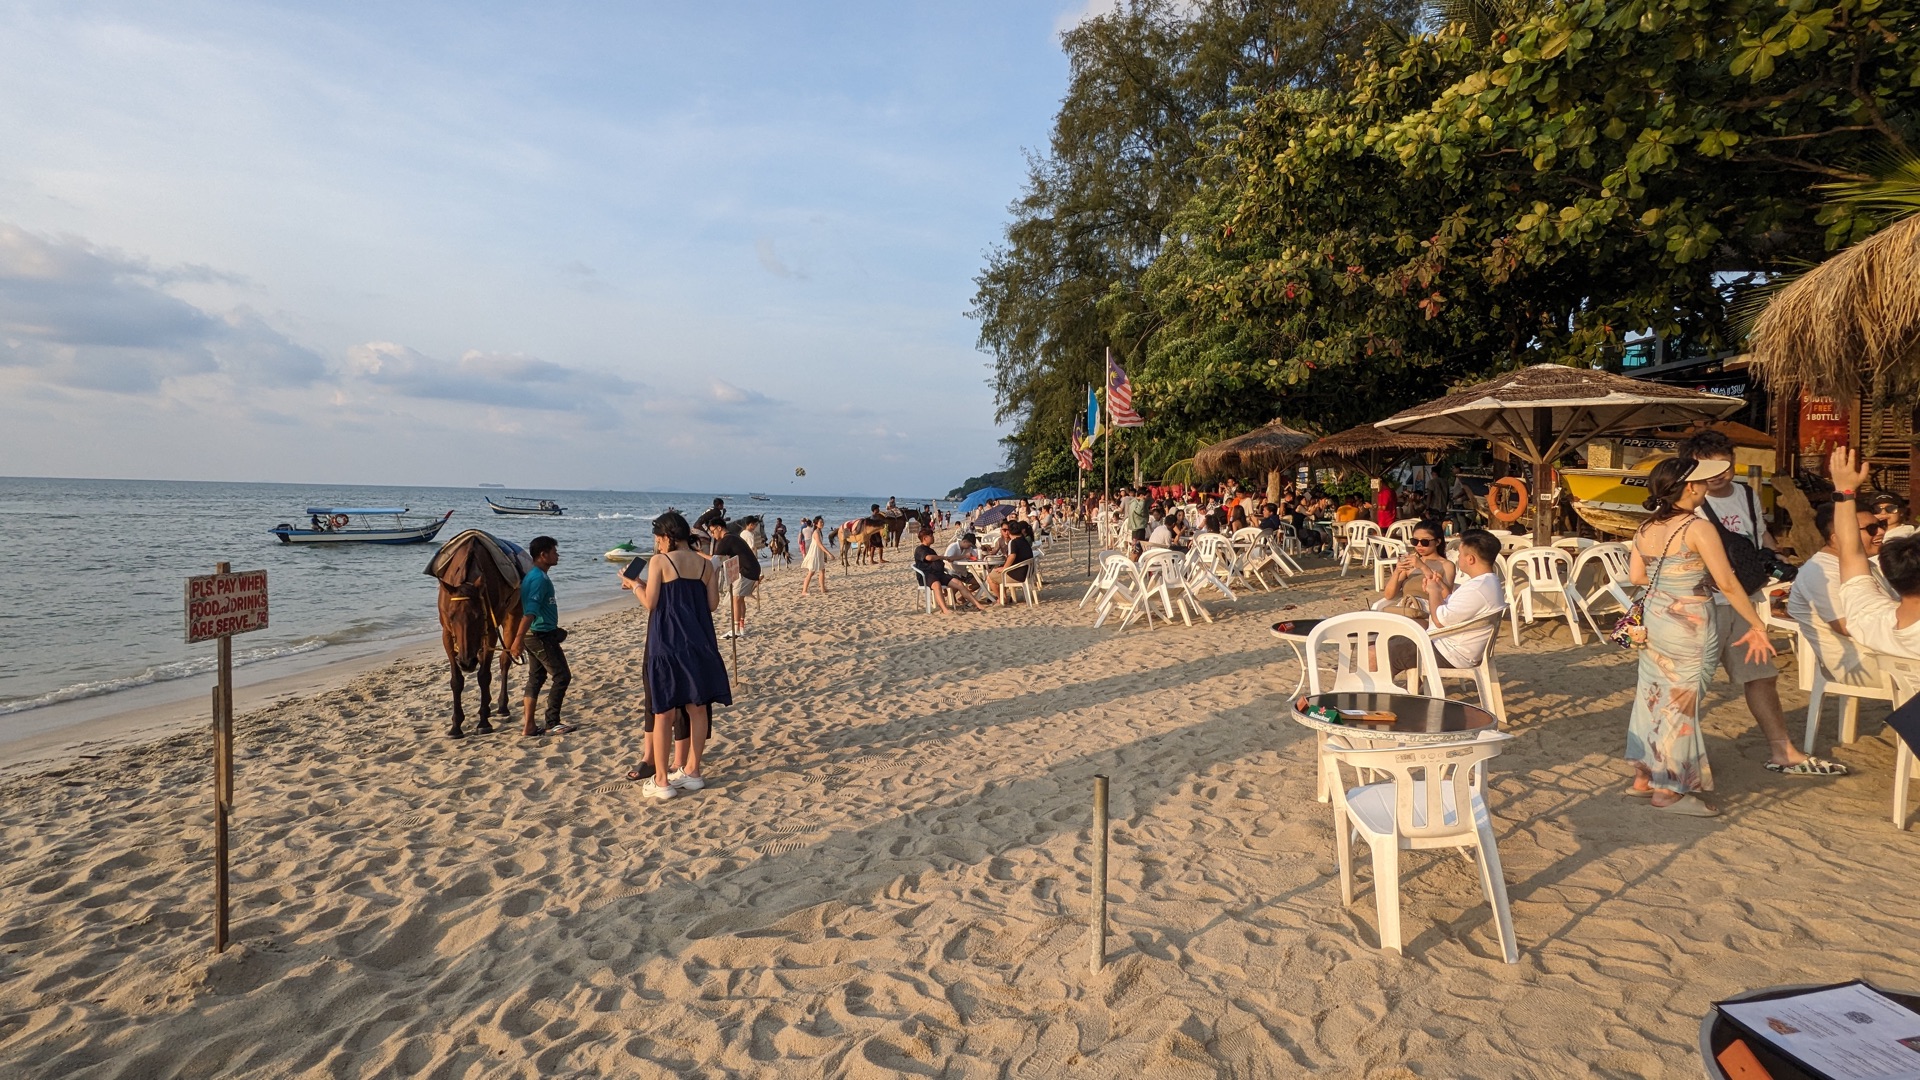
In 2026, the honest read on Batu Ferringhi is uneven: the subsale market is genuinely buyable, and the new-launch pipeline is real but not yet priced. Six upcoming projects sit in various pre-sales-gallery states — CapitaLand-branded, MRCB Land, Encorp, Ivory, Prinsiptek — but none has released the pricing pack, VP quarter, and unit mix that lets a buyer commit with real numbers. Meanwhile eleven completed condos and landed clusters trade on the strip from RM833 psf up, freehold, with a decade of visible track record. This is the read I give clients who walk in asking "new or subsale on the beach?" — the honest answer this year is subsale, and here's why.
Key takeaways:
- The new-launch pipeline is upcoming, not selling. Six projects — Ascott Residence, MRCB Land's Batu Ferringhi Residences, Enclave Seaview, The Oceanus, The Garden @ Island Resort, Prins Bay — sit in pre-launch. Teasers exist; pricing packs, unit mix, VP quarters, and in several cases even the definitive land title class have not been fully released. None currently has a live project page in our directory because none clears our data-quality bar for one.
- Subsale is where the depth is. Ten-plus verified freehold condos and landed clusters trade actively — from RM833 psf entry (By The Sea) up to RM1,440 psf top-stack, with landed superlinks and villas from RM420–711 psf on much bigger footprints.
- Foreign eligibility gate: the Penang Island floor is RM1,000,000 per unit — no title-class workaround. That rules out Iconic Vue (RM420–505k) and the smallest Ferringhi Residence stacks (RM750k) for foreign buyers. Everything else on this shortlist clears the floor.
- No LRT, ever. The Mutiara Line does not serve the northern beach corridor. Batu Ferringhi is a lifestyle and STR yield play, not a commuter play. If your job is in Bayan Lepas or you need to be in Georgetown daily, this is the wrong corridor.
- Short-term rental is the corridor's edge and its risk. Tourist demand is real; the regulatory picture on strata STR is tightening. A subsale with a proven income record and permissive house rules is a very different asset from a new launch where none of that is settled.
The Batu Ferringhi landscape in 2026
Batu Ferringhi is Penang Island's beach resort strip — the one stretch of coast where the beach is actually swimmable and the demand pattern looks like a resort town, not a suburb. Rasa Sayang, Shangri-La Golden Sands, Parkroyal and Hard Rock Hotel anchor the coastline, the night market runs seven nights a week, and the tourist mix (regional Asian short-haul, European long-haul in the cooler months, Malaysian domestic on weekends) has been building steadily since the post-2022 travel rebound. That is what makes this corridor different from every other prime-island postcode — and why the property mix here does not look like Gurney or Tanjung Tokong.
Everyday-life amenities are thinner. The nearest large mall is Gurney Plaza — call it 20 minutes on a good day, 45 on a bad one. There is one specialist hospital (Loh Guan Lye at Tanjung Bungah, about 20 minutes east), and international schooling means Uplands or Tenby with a 15–20 minute drive. There is no LRT here and there will not be — the Mutiara Line does not serve the northern corridor. If you need to commute to the Free Industrial Zone in Bayan Lepas, this is the wrong corridor. If you want beach lifestyle, a real STR yield story, or a lock-and-leave second home, this is the corridor.
Foreign-buyer economics apply exactly as they do anywhere else on the island: the RM1,000,000 minimum per unit, the 3% state levy on the full purchase price, the flat 8% stamp duty on the SPA and the MOT, LTV usually capped around 70% for a foreign borrower, and state consent taking about 3–4 months. There is no beachfront exemption. See the foreign-buyer guide for the full stack.
Why the new-launch side of this comparison is empty (right now)
I want to be direct here, because a lot of Batu Ferringhi coverage online is not. Six new launches are talked about on the strip: Ascott Residence Batu Ferringhi (Instant Icon Sdn Bhd under the CapitaLand-owned Ascott operator), Batu Ferringhi Residences (MRCB Land), Enclave Seaview Residences (Encorp Development), The Oceanus (Island Landcap), The Garden @ Island Resort (Ivory Properties, sitting inside the existing Island Resort estate), and Prins Bay (Prinsiptek). All six have some public presence — teaser sites, holding pages, occasional media mentions.
None of them currently has:
- A fully released pricing pack per unit type
- A confirmed VP quarter that would let me build a real cash-flow timeline
- Definitive land title class published (residential vs commercial vs commercial-HDA — the single variable most likely to move a foreign buyer's economics)
- Signed launch documentation I could stand behind under my licence
That is why none of them has a project page in our new-launches directory yet — the data quality is not there, and I would rather leave a gap than publish a shell page. When the sales galleries actually open and the packs release, they'll go up.
For a buyer today, the practical read is:
- If your timeline is this quarter or next, none of the six will close cleanly. Committing to a teaser-stage project is a 3–5 year exposure at pricing that hasn't been fixed. That is a big ask.
- Register interest across all six — it costs nothing, and when a pricing pack drops you want to be on the agent list.
- In the meantime, the subsale market is fully buyable — completed buildings, real prices, real income records, and 3–4 months to keys after SPA.
The subsale-vs-new-launch comparison people expect from a piece with this title will actually make sense in 2027, once one or two of the six have priced. This year, it is a subsale conversation.
The subsale stock worth viewing
Every project below is completed, freehold, and trades regularly. Prices are from my verified project database (last research pass 2026-08); verify unit-level pricing with the seller's agent before you sign.
The beachfront condos
By The Sea @ Batu Ferringhi is Selangor Dredging Berhad's beachfront development — three low-rise blocks, 138 units, freehold, completed 2015. It sits on the strip proper. RM950,000 to RM3,100,000, RM833–1,440 psf. The entry stacks scrape just under the RM1M foreign floor, so a foreign buyer starts one tier up. Zac's rating: 4.2. This is the closest thing on the market to "the branded-residence experience without the brand tax" — low density, real beachfront, and 11 years of visible track record. Land title in our data reads null; confirm the title class with the seller's solicitor before SPA.
The Marin @ Ferringhi is the newest large condominium on the strip by a clear margin — completed 2018 by Plenitude. RM1,158,000 to RM1,900,000, RM649–1,027 psf. Freehold. This is the sensible Batu Ferringhi buy rather than the glamorous one, and I mean that as a compliment — you get modern construction, contemporary layouts, and pricing that has not yet run to Pearl Residences levels. Zac's rating: 4.3.
Moonlight Bay is the low-density seafront play — 90 units split between villas and condovillas, freehold residential, completed 2010 by Ivory Properties. RM1,490,000 to RM2,950,000, RM710–752 psf. Zac's rating: 4.5. This is the "I want a house at the sea, but managed" answer. Density is genuinely low.
Pearl Residences @ Batu Ferringhi carries the highest starting PSF in this whole subsale set — RM2,200,000 up, RM678–740 psf for 3,095–3,359 sqft units. Freehold. Zac's rating: 4.4. Larger units, quieter positioning.
Ferringhi Pearl — RM1,400,000 from, RM450–600 psf, freehold, completed 2016. Zac's rating: 4.5. Pricing is competitive in absolute terms because the units are large — the psf reads lower than newer stock but the ticket size still lands solidly.
10 Island Resort is the modern (2012) freehold gated resort condo — 266 units plus 11 semi-D villas, by Ivory. RM535,000 to RM2,879,999, RM486–712 psf. Zac's rating: 4.4. The entry stacks are below the RM1M foreign floor, so foreign buyers start further up the stack.
Ferringhi Residence — RM750,000 to RM1,000,000, RM511–638 psf, freehold, 210 units, Mah Sing, completed 2015. Zac's rating: 4.1. The cheapest usable-size entry into the strip. The entire price band sits at or below the RM1M foreign floor — this one is effectively a Malaysian-buyer product. Foreign buyers should not price against this project directly; use it only as an area benchmark.
Ferringhi Residence 2 — RM1,064,800 from, RM505 psf, freehold residential, Mah Sing. Zac's rating: 4.2. The successor block, priced just over the foreign floor.
The landed stock
Island Resort Semi-Detached Villas — only 11 units, sizes 3,820 to 6,450 sqft, private lift and private plunge pool, from RM2,330,000, RM556–711 psf, freehold. Zac's rating: 4.5. Genuine luxury landed at Batu Ferringhi is a very small market; this is essentially it.
Ferringhi Hills — 3-storey superlink houses, 1,540 sqft of land, 3,255 sqft build-up. From RM1,350,000, RM420 psf, freehold residential. Zac's rating: 4.2. Genuine landed at a price that a lot of "landed" projects on the island can't match, because the sea-view stacks are further inland here.
La Ferringhi — RM1,318,000 from, RM450–600 psf for 2,750 sqft units. Zac's rating: 4.4. Sits in the middle of the Batu Ferringhi landed pack.
The affordable outlier
Iconic Vue — 232-unit freehold condo on Lorong Sungai Emas. Every unit 850 sqft. RM420,000 to RM505,000, RM494–594 psf. Zac's rating: 4.0. This is the strip's clearest single-format building. Below the RM1M foreign floor for the entire stack — Malaysian buyers only.
What to buy today, by buyer type
The STR investor
Subsale, clearly. You need three things a new launch cannot give you: a completed building, existing house rules on short-term rental that you can read before signing, and an income record you can underwrite. By The Sea and 10 Island Resort are the two that come up most often on my desk for this profile — beachfront positioning, existing operator activity in the building, and freehold. Assume 50–55% occupancy at RM450–600 a night for a well-presented unit through the peak months, dropping meaningfully in the low season. Do not use developer or brochure assumptions of 80% at top-of-band nightly rates — those numbers do not survive contact with the actual booking calendar.
Run your own numbers with the short-term rental calculator before you sign anything.
The MM2H retiree
Subsale, in almost every case. MM2H is a visa programme, not a property programme — the property purchase is independent of the visa status. If you already hold or are applying for MM2H (see the MM2H Penang guide), you are pricing lock-and-leave beach lifestyle. Subsale gives you the ability to walk the unit, see the sea view, hear the traffic, check the neighbours, and move in this year. A new-launch commitment today means renting through 2027 or 2028 while progress-billing a construction site.
The MM2H property threshold on the island (RM1M and a 10-year minimum hold) is met by nearly everything on this list except the affordable-tier outliers.
The own-stay upgrader
Subsale unless you have real patience. Own-stay upgraders in Batu Ferringhi usually want space, seaview and low density. The subsale stock — Moonlight Bay, Pearl Residences, Ferringhi Pearl, the Island Resort villas — delivers all three today at prices you can walk in and negotiate on. The upcoming new launches will deliver newer product with modern layouts, but with 3–4 years of construction risk, unpriced units today, and the standard developer premium over an equivalent subsale nearby. If moving in matters this year, subsale.
The branded-residence buyer
Wait, or find your brand elsewhere. No completed subsale in Batu Ferringhi is branded. The only branded piece in the pipeline is Ascott Residence — but until its pricing pack fully releases, "committing" to a brand you can't yet price is a leap of faith. If the branded-residence experience is the point of the purchase, either wait for Ascott's launch pack to drop, or look at branded stock in other corridors (there's an active Gurney/Tanjung Tokong branded-residence conversation).
The financing reality for a foreign buyer
Two numbers matter more than the interest rate:
- The Penang Island floor is RM1,000,000 per unit for a foreign buyer, always — no matter the tenure, no matter the title class. Below that, you cannot legally buy on the island. That kills Iconic Vue and much of Ferringhi Residence for foreign buyers before financing even enters the picture.
- Foreign LTV is about 70%, not 80 or 90. On a RM1.8M subsale that's roughly RM540,000 of your own money going in on the equity, plus roughly RM144,000 for the flat 8% stamp duty, plus roughly RM54,000 for the 3% Penang levy, plus legal and consent fees. That's the cash-in-hand number to plan against; check it with the affordability calculator.
On subsale specifically: the loan releases against a completed asset, so the LTV maths is clean at drawdown. New launch under the standard progressive schedule releases over 24–36 months — easier on cash flow while the building rises, but exposes you to any policy change (LTV, rate, foreign rules, Budget 2026's flat 8% foreign stamp duty which took effect 1 January 2026) during that window. For a foreign buyer specifically, that policy exposure is a real cost, not a rounding error.
MM2H holders get treated the same as other foreign buyers on the property side, contrary to what a few brochures suggest. The visa does not lift the RM1M floor, it does not change the levy, and it does not change the LTV cap. What it does is make the property qualifying-asset side of the visa easier — see the MM2H page for the full stack.
The catch — three of them, actually
No LRT, ever. Traffic on the coast road gets serious on Chinese New Year, on hotel-conference weekends, and any Saturday between March and October. The drive to Gurney is not always 20 minutes; sometimes it is 45. That is the corridor's structural cost.
Seasonality is real. STR occupancy sags in September–November and again in May. If your yield model assumes a flat 55% year-round, you have overstated income by 15–20%.
The upcoming pipeline is a queue, not a line. Six new launches at various stages of pre-launch will not all deliver on time and not all at their teaser positioning. If new-launch selection matters to you, register interest across all six, wait for pricing packs, then pick — do not commit to the first one that opens a sales gallery.
So — what do I actually do?
For a foreign buyer with a 2026 timeline: look at the subsale stock, pick the one whose completion year, view, and existing house rules match your plan, and move. By The Sea, The Marin, Moonlight Bay and Pearl Residences are the four I walk clients through most often — different price points, different densities, all completed and priced today.
For a buyer with a 3-year horizon and a preference for new construction: register for all six upcoming new-launch teaser lists, and wait for pricing packs. When one of them opens a real sales gallery, I'll write a proper project page and a follow-up piece pricing it against the subsale set above. That is not a piece I can honestly write yet.
Want me to walk one or two of the subsale options specifically — pull the current SPA prices, confirm land title, check the actual STR house rules — before you commit? That's the WhatsApp or foreign-buyer intro path.
Related reading
- Batu Ferringhi area guide — the corridor deep dive, amenity map, and typical rental bands
- Foreign-buyer guide to Penang — the RM1M floor, 3% levy, 8% stamp duty and full cost stack
- MM2H Penang guide — visa mechanics and the property qualifying-asset overlap
- Short-term rental (Airbnb) yield calculator — for stress-testing Batu Ferringhi STR assumptions
Sources. Project prices, PSF bands, tenure and land title verified against my verified project database (last research pass 2026-08). Regulatory constants (RM1M island floor, 3% state levy, flat 8% stamp duty effective 1 January 2026 under Budget 2026, foreign LTV band, 3–4 month state consent) verified against Penang state guidance and current LHDN practice. Batu Ferringhi tourism and hotel operators verified against publicly listed hotel operations on the strip. Where developer teasers exist but pricing packs have not released, projects are named but not linked; they'll go up on our new-launches directory when the data quality warrants it.