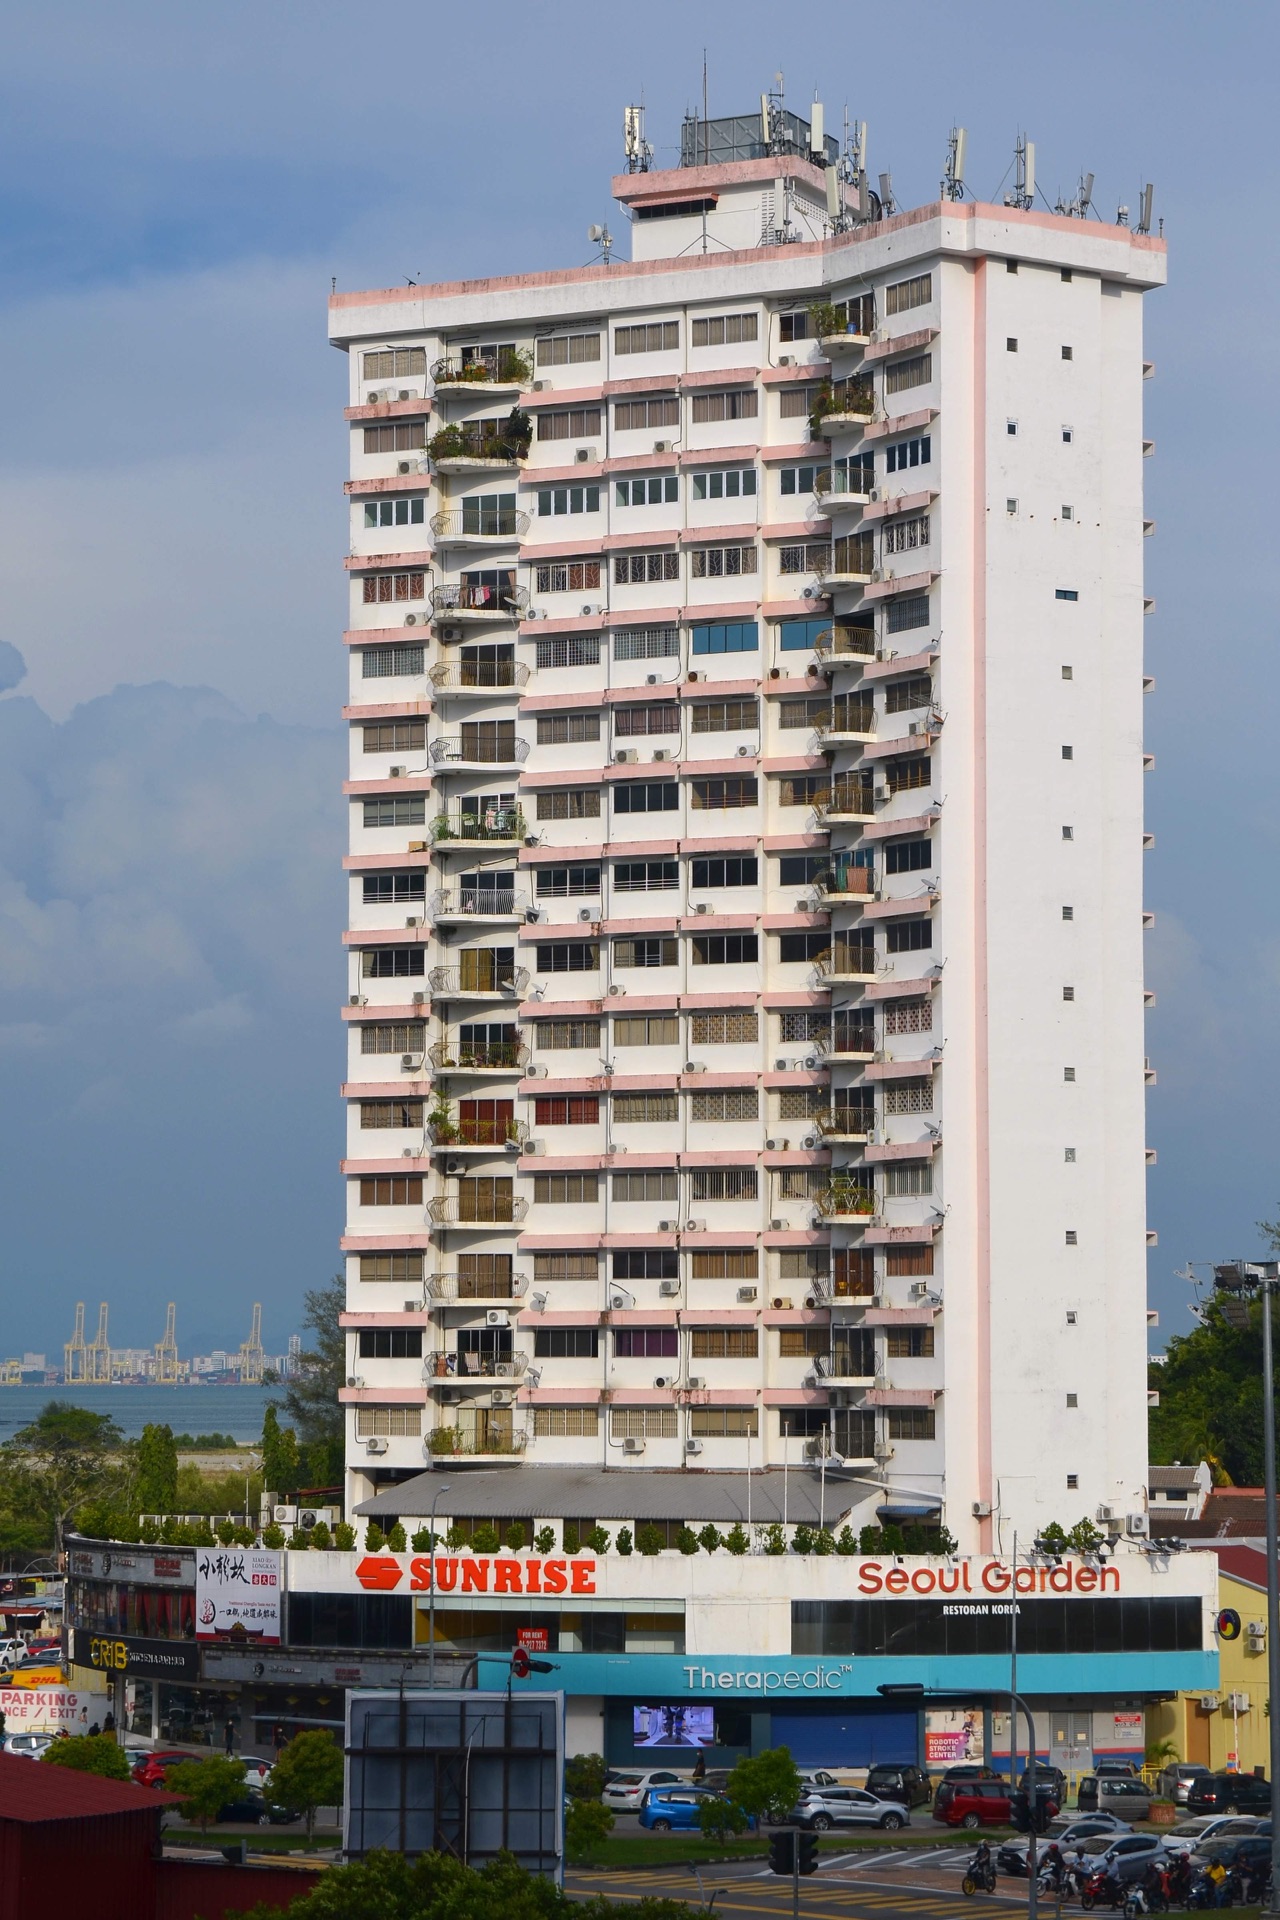
Everyone quotes RM6,000/month for retirement in Penang. That number is from 2018 and it hasn't been true for four years. Here's what RM10,000/month actually buys a retired couple in Penang today — housing, healthcare, groceries, one restaurant meal a week, and the one thing every retiree I've advised over-budgets and every one of them under-budgets.
I've walked five retired couples through this in the last twelve months — three British, one Hong Konger, one Singaporean. Their real ledgers looked nothing like the round numbers floating around Reddit and the expat Facebook groups. What follows is the honest version, with the arithmetic shown, priced in September 2026 ringgit (£1 ≈ RM5.60, S$1 ≈ RM3.35, HK$1 ≈ RM0.55).
Key takeaways:
- The RM10,000/month ledger breaks roughly into RM3,500 housing, RM1,800 groceries and dining, RM1,400 healthcare and insurance, RM1,200 transport, RM1,000 utilities/telco/leisure, RM1,100 miscellaneous and buffer. Change any one line and the rest tightens.
- Foreign retirees cannot buy under RM1,000,000 on Penang Island — the state floor never varies by title class, and a 3% levy sits on top. Renting is the honest fallback for the first year.
- Healthcare is the line everyone under-budgets. Consultations at Gleneagles Penang run RM100–300, but one moderate hospital stay is RM18,000–35,000. Private insurance premiums for a couple in their 60s are RM8,000–14,000 a year, not the RM3,000 people quote.
- Groceries and dining are the line everyone over-budgets. Wet-market shopping plus a Village Grocer top-up for two comes in around RM1,200/month; a hawker dinner is still RM10–15 a head.
- MM2H's Silver tier (RM500K fixed deposit + RM600K property, 5-year visa) is the entry point since the 2024 revamp, but Gold (RM1M FD + RM1M property, 15 years) is what most Penang-island buyers actually take because the RM1M property floor already applies.
The RM10,000/month ledger — line by line
This is the ledger a couple I placed in Tanjung Bungah last year actually runs. Owned condo (no mortgage), one shared car, insurance held since their fifties, one restaurant meal a week, one short domestic trip a quarter.
| Line | RM/month | What it covers |
|---|---|---|
| Housing — maintenance + sinking fund | 550 | Mid-tier condo, ~1,300 sqft, RM0.35/sqft management fee including sinking |
| Housing — assessment + quit rent | 150 | Split monthly, actually paid half-yearly |
| Housing — home insurance + minor upkeep | 200 | Landlord/homeowner policy + repairs float |
| Utilities — electricity | 450 | Two aircon units running most evenings, tropical climate |
| Utilities — water + gas + internet | 220 | Unifi 500Mbps + PBAPP + LPG cylinder |
| Mobile — two lines | 180 | Two Maxis/Celcom postpaid, roaming-ready |
| Groceries — wet market + supermarket | 1,200 | Two adults, home-cooked most days |
| Dining out — hawker + casual + one nicer meal | 700 | ~4 hawker dinners, 2 casual, 1 restaurant per week |
| Transport — car (loan-free) | 1,200 | Insurance, road tax, fuel, parking, servicing, depreciation |
| Healthcare — routine + medications | 350 | GP visits, ongoing prescriptions, dental cleanings |
| Health insurance — couple in their 60s | 1,050 | Verified band; see healthcare section |
| Domestic help — part-time housekeeper 2x/week | 400 | Standard rate RM50/session |
| Leisure — gym, hobbies, cinema, subscriptions | 300 | One gym membership, Netflix/Spotify, occasional |
| Travel float — quarterly domestic trip | 400 | Averaged; KL, Langkawi, Cameron Highlands |
| Buffer / gifts / one-off | 650 | This line always disappears; keep it |
| Total | 8,000 | Base run-rate |
That's RM8,000, not RM10,000. The RM2,000 gap is where discretionary lives — a second car, more travel, more dining out, a maid five days a week instead of two, or the compounding drift of everything ticking up 4–5% a year. Almost every couple I've watched settles at RM9,500–10,500 within their second year, once the honeymoon frugality wears off.
Change any of the assumptions and the number moves fast. Renting instead of owning adds roughly RM2,500–4,000/month for a comparable unit. Taking insurance out at 65 instead of 55 doubles the premium. Running two cars adds another RM1,200. Sending grandchildren home to see them once a year is a line item all of its own.
The one thing retirees over-budget, and the one thing they under-budget
Every couple I've sat down with over-budgets groceries and eating out. The mental model is European supermarket prices minus 40%. The reality is that a wet-market run at Pulau Tikus or Tanjung Bungah — fish, prawns, greens, fruit — costs half that. A Village Grocer or Ben's top-up for imported cheese, wine, olive oil, and the coffee they refuse to give up brings it back up, but nowhere near what people brace for. RM1,200/month feeds two adults who eat well. Add RM700 for one nicer restaurant meal a week and daily hawker dinners and you are done.
Every couple I've sat down with under-budgets healthcare and insurance. They anchor on the consultation fee — RM100–300 at Gleneagles Penang — and forget that the reason you fly to Penang for treatment is not the consultation, it's the surgery and the diagnostics. A single-room stay is RM380/night at Gleneagles, but the surgeon, the imaging, and the theatre time turn a three-night moderate cardiac admission into an RM18,000–35,000 bill. If you don't have insurance, that number comes off the fixed deposit. If you do, and you took it out in your late 60s without underwriting a prior condition, the exclusion clause bites and it also comes off the fixed deposit.
Take insurance out earlier than you think, is the short version. And underwrite honestly — Malaysian insurers will pay what they promised, but they will also enforce exclusions to the letter.
Housing at RM10K/month — three paths
There are three routes into housing for the RM10K/month reader. Rent, buy subsale, buy new-launch. All three work; they solve different problems.
Path 1 — Rent for the first year (the honest default)
A furnished 1,200–1,600 sqft condo in Tanjung Tokong, Tanjung Bungah or Pulau Tikus rents for RM3,500–6,500/month in September 2026 depending on view, age, and building. That's the single biggest concentration of expat retirees on the island, and the market is deep enough that you'll have three or four real options within a fortnight.
Renting is not a lesser choice — it's the correct choice if you're unsure whether Penang suits you. I've seen two couples out of the last five sell within eighteen months because the humidity, the driving, or the distance from grandchildren was heavier than they'd predicted. Renting first meant they lost a deposit's worth of transaction friction, not RPGT and the 3% state levy.
Path 2 — Buy subsale (the value route)
Verified, publishable, and clearing the RM1,000,000 foreign floor as of today:
- Mira Residence — Tanjung Bungah. From RM1,070,000, ~RM734 psf, freehold, residential title. Mid-rise, ~1,400 sqft three-bed layouts, sea-glimpse from the higher floors. This is the honest sweet spot for a retiree who wants space, freehold, and legal foreign eligibility without stretching.
- Codrington Residence — Pulau Tikus. From RM1,400,000, ~RM1,058 psf, freehold, residential title. Boutique, walkable to Gurney, Gama supermarket, and the cluster of clinics on Burma Road. You pay for location, not size.
- Ferringhi Residence 2 — Batu Ferringhi. From RM1,064,800, ~RM505 psf, freehold, residential title. The lowest PSF on this list because Batu Ferringhi is quieter and further from the hospitals. If you want beach walks and a garden feel and don't mind the 25-minute drive to Gleneagles, this is where the ringgit stretches furthest.
Path 3 — Buy new-launch (the certainty route)
- Waterstone — Tanjung Bungah. From RM1,287,000, freehold. Currently selling, developer-warranted, price on application for the sea-facing stack — confirm the specific unit's PSF with the developer, as the derived rate depends on whether the size is nett or built-up.
- Crown Penang — Tanjung Tokong. From RM704,000, ~RM955 psf, freehold. Below the RM1,000,000 foreign floor — this is a local-buyer or MM2H-Silver-plus-topped-up option, not a straight foreign purchase. I've included it because the ledger reader needs to know why the "cheap Penang new launch" they saw on Instagram doesn't apply to them.
The rent-vs-own arithmetic
Take Mira Residence at RM1,070,000. A foreign buyer's cash-in is roughly:
- Purchase price: RM1,070,000
- 8% foreigner stamp duty (MOT/SPA flat rate): RM85,600
- 3% Penang state levy: RM32,100
- Legal + disbursements + valuation: ~RM18,000
- Total cash to complete: ~RM1,205,700
At 70% foreign LTV and today's BNM OPR of 2.75% (so a ~5.15% mortgage rate), the interest-only cost on RM749,000 is about RM3,215/month; add ~RM1,000 principal on a 20-year loan and you're at RM4,200/month, plus the RM900/month of maintenance/assessment/insurance already in the ledger. The comparable rental is RM3,500–4,500/month, no cash-in, no state consent wait.
On monthly outgoings, rent wins for the first five years. On an 8–10 year horizon, ownership pulls ahead because rent inflates and the mortgage doesn't. On tax and estate certainty, ownership wins outright. And for MM2H Gold, ownership is the requirement, not a choice.
Use the affordability calculator to run your own version, and the RPGT calculator to see the exit cost — RPGT for foreigners is 30% for the first five years and 10% from year six, and it never reaches 0%, unlike the citizen scale.
Healthcare — what it actually costs
Penang's private hospital cluster is the real reason foreign retirees choose it over Phuket or Chiang Mai. The two anchors are Gleneagles Penang (~380 beds, JCI-accredited since 2016) and Island Hospital (~600 beds, the largest private hospital on the island). Both take foreign patients and both bill in ringgit.
Verified 2026 room rates at Gleneagles Penang:
- Four-bedded: RM160/night
- Two-bedded: RM195/night
- Single: RM380/night
- VIP: RM480/night
- ICU/CCU: RM400/night
A specialist consultation is RM100–300. What breaks the budget is not the room — it's the procedure. Ballpark, all-in bills a retiree should have insurance to absorb:
| Event | Ballpark range |
|---|---|
| Annual check-up + basic bloods, two people | RM1,500–2,500 |
| Cataract surgery, one eye | RM7,000–12,000 |
| Angioplasty with one stent | RM28,000–45,000 |
| Three-night moderate cardiac admission | RM18,000–35,000 |
| Total knee replacement | RM35,000–55,000 |
Private couples insurance at 60–65, fresh underwriting, moderate cover: RM8,000–14,000/year — RM650–1,200/month. If you're already on a policy from your home country that covers Malaysia, keep it; it's almost always cheaper than starting fresh. If you're not, the honest advice is to take a Malaysian policy out before you land, not after your first check-up flags something.
The MM2H angle — which tier the RM10K/month couple actually needs
Malaysia's MM2H programme was restructured under MoTAC in 2024 into three tiers (Silver, Gold, Platinum). As of today the requirements are:
| Tier | Fixed deposit | Property minimum | Visa validity |
|---|---|---|---|
| Silver | RM500,000 | RM600,000 | 5 years, renewable |
| Gold | RM1,000,000 | RM1,000,000 | 15 years |
| Platinum | RM5,000,000 | RM2,000,000 | 20 years |
Two things the ledger reader has to internalise:
- The RM600,000 Silver property figure does not override the Penang Island foreign floor. On the island you still need to spend RM1,000,000 minimum. Silver is a mainland proposition (Seberang Perai) or a rent-only proposition if you want to stay in Tanjung Tokong.
- Gold is what most island-based retirees pick. The RM1M FD sits earning ~3% interest at a Malaysian bank (the visa allows partial withdrawal for property, medical, and education after year one), and the RM1M property purchase is already your foreign floor. The 15-year visa removes renewal friction. This is the tier that fits the RM10K/month reader on the island.
Applications now must go through a MOTAC-licensed MM2H agent — direct applications are no longer accepted. I don't run MM2H applications myself; I introduce clients to licensed agents I've worked with for years. Read the fuller breakdown at /mm2h-penang/ and the general foreign-buyer rules at /foreign-buyers/.
Where the RM10K/month couple actually lives
Not everywhere on the island works for a retiree. Here's the honest read on each area at this budget:
- Tanjung Tokong — Straits Quay, Andaman, walkable to Tesco and Island Plaza. The default landing zone for expats, 15 minutes to Gleneagles, mostly high-rise. Owned condos at RM1.1–1.5M, rent RM4,000–6,000. Trade-off: traffic during the school run is real.
- Tanjung Bungah — quieter, greener, slightly older buildings, better value per PSF. 20 minutes to Gleneagles. Owned at RM1.0–1.3M, rent RM3,500–5,000. Trade-off: fewer walkable amenities, you'll drive more.
- Pulau Tikus — the walkable retiree's choice. Wet market, cafés, clinics, and Gurney Plaza on foot. Boutique low-rise stock at RM1.3–1.8M, rent RM4,500–6,500. Trade-off: parking is genuinely awful and units are smaller.
- Gurney Drive — waterfront prestige, luxury condos. Comfortably above RM10K/month once you factor the maintenance fees and the higher entry price. Skip unless you're really at RM12–15K.
- Batu Ferringhi — beach, resort atmosphere, larger units per ringgit. 25–30 minutes to Gleneagles by car, no LRT (the Mutiara Line does not serve the northern corridor). Owned at RM1.0–1.4M, rent RM3,500–5,000. Trade-off: you must be comfortable driving, and hospital runs are a real journey.
- George Town (heritage core) — for the walkable, café-and-culture retiree who doesn't mind heritage-shophouse maintenance quirks. Foreign eligibility is complicated inside the heritage zone; talk to a lawyer before you sign anything.
- Bayan Baru — south island, closer to the airport, cheaper. Retirees who want to fly back regularly and don't need to be in the north end up here. Muze @ PICC from ~RM780K on the local side, but again — RM1M floor for a foreign buyer.
Deeper reads on each are in the area guides.
What happens if you scale to RM7K or RM15K
At RM7,000/month you can still retire comfortably in Penang, but three things have to give: you rent instead of own, you don't run a car (Grab budget of RM500–700/month covers a Tanjung Tokong or Pulau Tikus couple), and you take a lower-tier insurance policy or self-insure the first RM50,000 of any hospital admission. This works for a couple in their early 60s with clean health, and it stops working the moment either of you has a serious diagnosis.
At RM15,000/month the marginal ringgit buys a bigger, sea-facing unit; a full-time helper instead of part-time; higher insurance cover with lower deductibles; a domestic trip every month instead of every quarter; and — the biggest single upgrade — the ability to fly home twice a year in business class or fly grandchildren to Penang. Most retirees I've placed find RM12,000 is the "no-anxiety" number; RM15,000 is where the lifestyle genuinely opens up.
If you want to sanity-check your own version against real market data, the Penang Price Index tracks the median PSF by area monthly, and short-term-rental yields tell you what a spare bedroom in your condo could earn on Airbnb if that's part of your plan.
Sources
MM2H tier structure — MoTAC (Ministry of Tourism, Arts and Culture) 2024 revised guidelines, cross-referenced with licensed-agent published guidance (September 2026). Gleneagles Penang room rates and consultation bands — Gleneagles Hospital Penang official rate card (2026). Bank Negara Malaysia OPR at 2.75% as of the latest MPC statement. Penang state foreign-buyer floor (RM1,000,000 island, RM600,000 mainland) and 3% levy — Penang State Government policy, standing since 2021 revision. Foreigner MOT/SPA stamp duty flat 8% — LHDN. RPGT foreigner schedule (30% years 1–5, 10% year 6+) — LHDN RPGT Act schedules.
This is a working ledger, not personalised financial advice. Every couple's real number depends on health status, home-country tax residency, currency risk on the pension side, and whether you plan to keep property back home. If you'd like to walk through your own version, my WhatsApp is on the page footer.