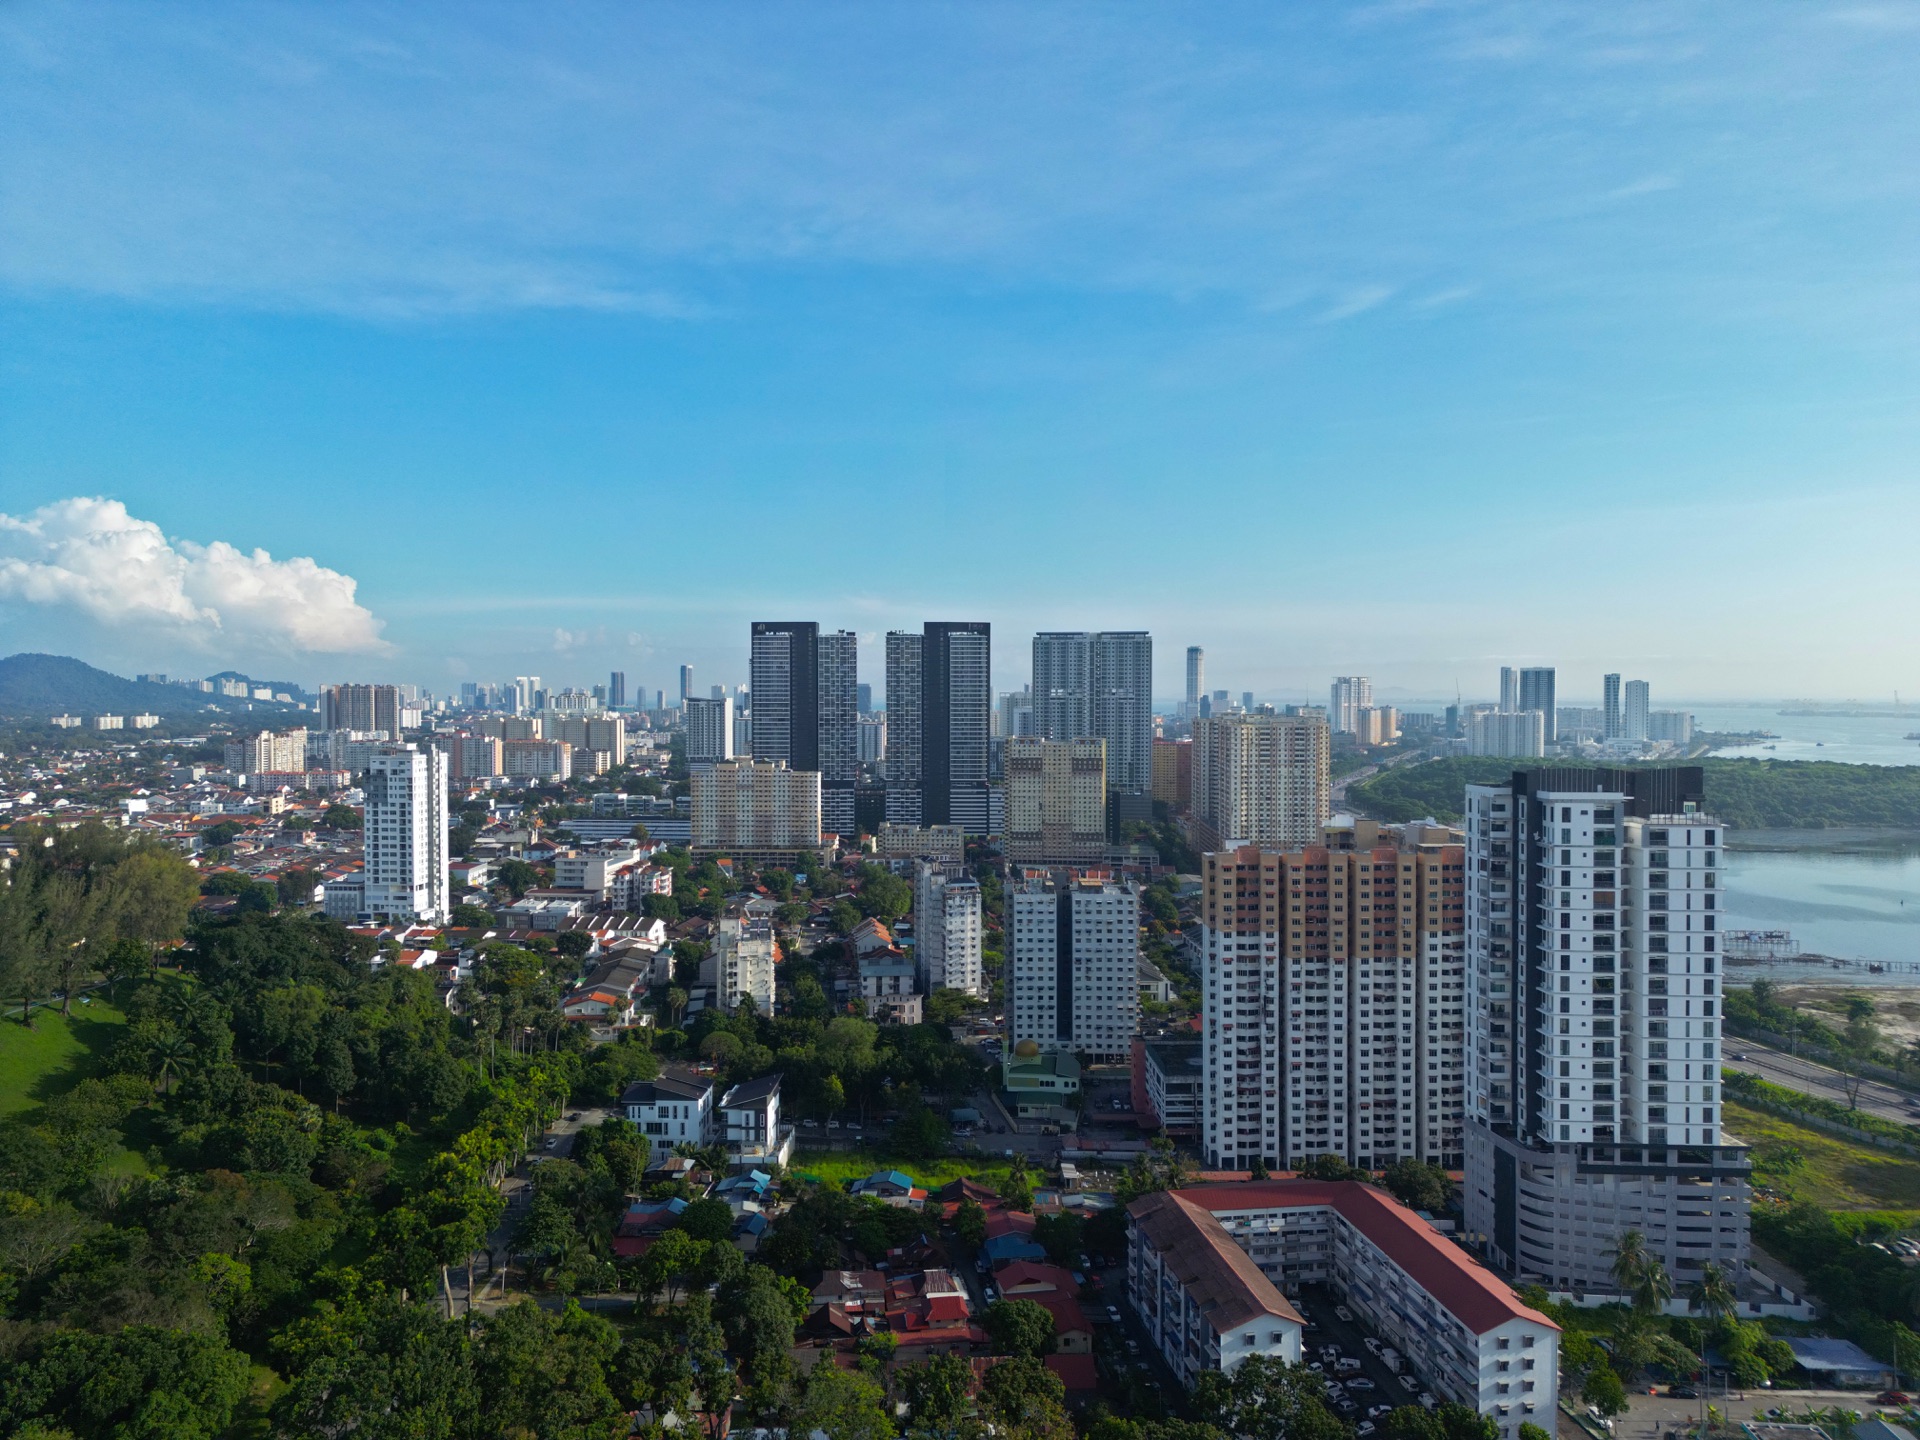
A Penang teacher, nurse or police officer can now borrow up to RM1 million from the government at a fixed 4% to 4.5%, and for the first time, buy a second home without paying off the first.
Both changes took effect on 4 October 2026. The Public Sector Home Financing Board (LPPSA) raised its ceiling from RM750,000 to RM1 million, and it now accepts a second financing while the first is still running. On the island, the old RM750,000 limit kept most civil servants out of landed homes and the better condos. RM1 million changes that.
Key takeaways:
- New ceiling: up to RM1 million, for applicants with net income above RM10,000 a month. Lower incomes get lower ceilings.
- Rates: 4% on the first RM750,000, 4.5% on the portion above it.
- Second home: allowed before the first is settled, up to 90% financing, if your first loan's deductions have started and you have no arrears.
- What it buys in Penang: new island condos in Jelutong and Queensbay, completed condos in Tanjung Bungah, Pulau Tikus and Gelugor, and freehold landed homes on both sides of the bridge.
What exactly changed
The higher ceiling was announced in Budget 2026, and LPPSA set out the details in an information notice dated 25 September 2026. They apply to applications from 4 October 2026.
The interest is charged in two layers. The part of your financing up to RM750,000 costs 4% a year, LPPSA's existing rate. Only the part above RM750,000 costs 4.5%. So stretching from RM750,000 to RM1 million doesn't reprice the whole loan.
The ceiling depends on income. RM1 million is for net income above RM10,000 a month; at exactly RM10,000 it's RM950,000, and at RM2,500 or less it's RM280,000. As EdgeProp put it, the RM1 million ceiling doesn't automatically entitle anyone to that amount: income, repayment capacity and the valuation still decide.
What it costs a month
| Financing | Over 30 years | Over 35 years |
|---|---|---|
| RM500,000 (all at 4%) | about RM2,390 | about RM2,210 |
| RM750,000 (all at 4%) | about RM3,580 | about RM3,320 |
| RM1,000,000 (RM750,000 at 4%, RM250,000 at 4.5%) | about RM4,850 | about RM4,500 |
These are my calculations. Your actual tenure depends on your age and LPPSA's rules, so check the exact figure when you apply.
The bigger difference from a bank is the margin. Banks usually lend up to 90% on a first or second home, so on a RM900,000 home you'd find RM90,000 plus costs yourself. LPPSA can finance up to 100%. That's why the new ceiling matters: it moves the RM750,000-to-RM1-million band, where most island family homes sit, into reach without a large deposit.
The second home: the bigger change
Until now, a civil servant had to settle the first LPPSA financing before taking another. From 4 October, you can apply for a second financing if:
- salary deductions for your first financing have started,
- you have no arrears on it, and
- you pass the repayment assessment for both.
The second financing goes up to 90% while the first is still running, or 100% if the first is settled. The RM1 million ceiling and the two rate layers apply to both financings together, so it's not RM1 million each.
In practice, this suits a civil servant who bought a starter apartment years ago and now wants a family home without selling the first. It also suits one who wants to buy near a new posting. Keep the first home and let it out, and use the rent to support the second repayment, as long as the assessment allows it.
What RM750,000 to RM1 million buys in Penang
This is the new band, the homes the old ceiling put out of reach.
New launches on the island:
- Alton Skyvillas, Jelutong, freehold condo from about RM898,560
- Setia SV2, Jelutong, freehold condo from about RM969,000
- Queens Residences Q3, Queensbay, freehold condo from about RM890,000
Completed condos on the island, where you can see the unit and move in sooner:
- Pearl View, Tanjung Bungah, from about RM758,000
- Pearl Regency, Gelugor, from about RM790,000
- Arcadia, Pulau Tikus, from about RM850,000
- Mira Residence, Tanjung Bungah, from about RM850,000
Freehold landed homes on the island, rare at this price:
- Begonia @ Botanica.CT, Balik Pulau, two-storey semi-Ds from about RM804,000
- Sunway Cassia, Batu Maung, from about RM920,000
- Tierra Residences, Bayan Lepas, from about RM930,000
New landed homes on the mainland:
- Embun Hills, Bukit Mertajam, from about RM803,000
- Everine @ Eco Sun, Batu Kawan, from about RM814,880
Prices are developer prices for new launches and asking prices for completed homes, as of October 2026. Completed homes vary a lot by floor and condition, so check the actual unit.
One caution. LPPSA finances homes for its own rules on property type, and some serviced apartments in Penang sit on commercial title. Before you book a serviced apartment, ask LPPSA or your lawyer whether that title qualifies.
Combine it with the Budget 2027 stamp duty break
If this is your first home, the Budget 2027 stamp duty exemption is proposed to cover first homes up to RM750,000 for SPAs signed from 1 January 2027: fully exempt up to RM500,000 and half off the rest. Above RM750,000 there's no exemption, so the two measures overlap only for first homes up to RM750,000. The exemption is still a proposal until it's gazetted.
Zac’s Take
Zac Ong
The second-financing rule is the bigger news for Penang civil servants, not the RM1 million headline. If you already own a starter flat on LPPSA, you no longer have to sell it to upgrade. Keep it, let it out, and buy the family home. Just check your income tier first: RM1 million is only for net income above RM10,000, and the ceiling covers both loans together. And if you're looking at a serviced apartment, confirm the title qualifies before you pay a booking fee.
Tell me your posting, budget and whether it's your first or second home, and I'll shortlist new and completed homes that fit your LPPSA ceiling.
Sources: LPPSA information notice of 25 September 2026 on the 2026 improvements to public sector housing financing, as reported by EdgeProp and others; Budget 2026 announcement of the RM1 million ceiling. Repayments are my own calculations. Project prices are from developer price lists and portal listings in October 2026.
Disclaimer: This is general information, not financial advice. LPPSA decides eligibility and amounts; confirm with LPPSA before you commit to a purchase.